Not every buyer group is in the market at the same time, and Q4 2026 is making that distinction sharper than usual. Over-the-road carriers are sitting on their hands. Freight rates are subdued, smaller operators are controlling costs, and Class 8 long-haul demand is still working through the hangover from the 2025 correction. That part of the market is not where dealers should be spending marketing budget right now.
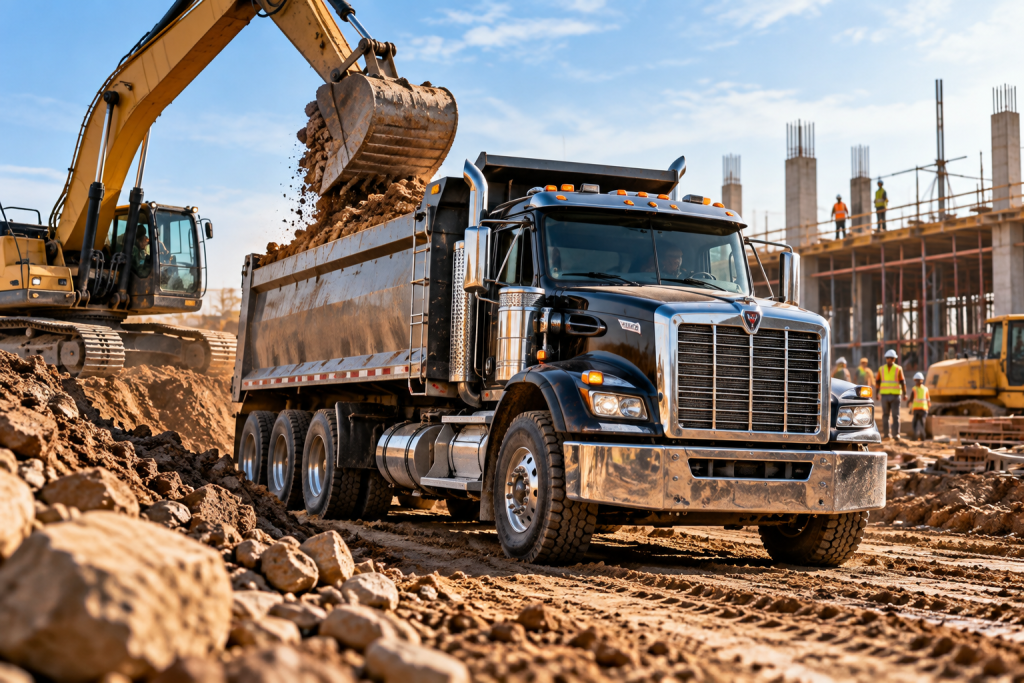
The segments that are buying in Q4 2026 are different: construction fleets, infrastructure contractors, utility operators, and government-adjacent buyers who are executing deferred replacement cycles on aging vocational equipment. The average commercial truck age in the US has reached 12.8 years, the highest level since the Great Recession, according to S&P Global and NTEA data published by Trucks, Parts, Service. That number creates real buying pressure in specific segments where deferred replacement is no longer practical.
This article is about which buyer types are active right now, what is driving their purchase decisions, and what dealers need to do differently to put their inventory and capabilities in front of those specific buyers rather than marketing broadly to a market that is only partially open.
The Two-Speed Market That Defines Q4 2026
The commercial truck market in 2026 is running at two speeds and dealers who treat it as one market are misallocating their marketing spend. Long-haul carriers and over-the-road fleets are throttled back. Vocational, construction, energy, and infrastructure-related segments are the active buyers. According to MonitorDaily’s 2026 market outlook, construction, energy, and infrastructure segments are providing a steady demand base and vocational trucks are insulated from the softer conditions affecting long-haul carriers.
The practical implication for a dealer is straightforward: a homepage message and marketing campaign aimed at owner-operators and long-haul fleet managers is talking to the quiet half of the market. The same budget aimed at construction companies, utility contractors, municipal buyers, and infrastructure project operators is talking to the active half.
Vocational trucks are insulated from the softer conditions affecting long-haul carriers. Construction, energy, and infrastructure segments are the steady demand base in Q4 2026.
Who Is Actually Buying Right Now
Construction and Infrastructure Contractors
Federal infrastructure spending from the Infrastructure Investment and Jobs Act continues to flow into project execution in 2026, generating sustained demand for dump trucks, flatbeds, crane trucks, and heavy spec vocational units. Contractors executing multi-year projects are not waiting for a market signal to buy — they have work on the books and equipment requirements attached to it. According to Hackney’s 2026 dealer market analysis, construction is one of the primary segments with active buying and available inventory depth, making it a window for dealers who can reach those buyers with relevant spec detail.
Construction buyers are purchasing against project specs, not browsing. A dump body with a specific payload rating, a crane truck with a particular boom capacity, a flatbed configured for oversized load transport — these are not general commercial truck searches. Dealers who can present inventory with the exact spec fields a contractor’s procurement team needs to evaluate a unit are far more likely to generate an inquiry than dealers whose listings show only make, model, and mileage.
Utility and Energy Operators
Utility fleet replacement is running on a compressed timeline in 2026. Equipment that was deferred during the supply chain disruptions of 2021 and 2022 has now aged past practical thresholds, and utility operators are replacing it. Fleet Rabbit’s 2026 aging fleet analysis notes that maintenance costs for vehicles beyond 10 years average 30 to 40 percent higher than for units in the 5 to 7 year range — a cost signal that triggers replacement decisions independent of market conditions.
For dealers, the utility segment is particularly valuable because it tends to purchase in multiple units rather than singles. A utility operator replacing end-of-life equipment often needs several units in the same body configuration. One qualified inquiry in this segment has materially different revenue potential than a single owner-operator inquiry.
Government and Municipal Buyers
Of the top five vocational registration categories tracked by S&P Global in 2025, government was the only one that showed a year-over-year increase. That trend is continuing into 2026 as municipal budgets that were frozen during the post-pandemic fiscal adjustment period begin to release for fleet replacement. Trucks, Parts, Service NTEA analysis identifies government registrations as an outlier in an otherwise flat vocational registration environment.
Municipal buyers operate on fiscal year timelines with budget windows that close at the end of the calendar year. A government fleet manager with Q4 budget to spend before December 31 is one of the highest-urgency buyers in the market. Dealers who are not visible to municipal procurement departments before Q4 are often invisible during the buying window itself.
Government was the only vocational registration category to show year-over-year growth in 2025. Municipal and government buying activity is continuing into Q4 2026 with fiscal year budget deadlines driving urgency.
What These Buyers Need Before They Contact a Dealer
Vocational buyers in construction, utility, and government segments share a common purchasing behavior: they arrive with specs. They are not exploring options — they have a body type, a duty class, a payload requirement, and sometimes a cab configuration already defined before they make first contact. According to Work Truck Online’s Q2 2026 commercial vehicle data report, fleet managers in 2026 are cycling vehicles more slowly and making more deliberate replacement decisions — which means the research phase before contact has lengthened.
A dealer whose marketing does not match that evaluation process is generating awareness without generating inquiries. The buyer arrives, cannot confirm the unit meets the specs they need, and moves on without contacting anyone.
What these buyers need to see before they will make contact:
- Body type and upfit configuration clearly stated — not inferred from photos
- GVWR, payload capacity, and axle rating as individual fields, not buried in a description paragraph
- Availability status and stock number so they can reference the unit in internal approval processes
- Service capability for the makes they operate — particularly for multi-unit government and utility accounts
- A fleet or multi-unit inquiry path that signals the dealer understands commercial transactions
How to Adjust Marketing Toward These Segments
Lead With the Application, Not the Unit
A construction buyer does not search for a truck. They search for a dump truck with a 14-cubic-yard body or a flatbed rated for a specific payload. Marketing copy and listing titles that lead with the application — not just the OEM and model year — connect with how these buyers are actually searching. A listing titled ‘2024 Kenworth T880’ is less findable by a buyer searching ‘tri-axle dump truck for infrastructure work’ than one titled ‘2024 Kenworth T880 Tri-Axle Dump — 16 Cu Yd Body, 58,000 lb GVW.’
Target Fiscal Year Urgency in Q4 Messaging
Government and municipal buyers with December 31 budget deadlines respond to messaging that acknowledges their timeline. A marketing email or platform listing that notes availability and lead time for delivery before year end speaks directly to the urgency a municipal fleet manager is already feeling. This is not a promotional tactic — it is relevant information to a buyer who has a budget window that closes in weeks.
Position Service as Part of the Sale for Multi-Unit Buyers
Utility operators and construction companies making multi-unit decisions are evaluating the dealer’s service capability alongside the unit itself. A dealer who can support five identical spec units under a fleet maintenance arrangement is worth more to that buyer than a dealer who sells them the same five units with no service depth. Hackney’s dealer market analysis specifically highlights that dealers who offer technical expertise in body integration and fleet support are converting vocational buyers at higher rates than those operating as transactional retail sellers.
Separate Your Messaging by Segment
A single homepage message cannot speak to a construction contractor, a utility operator, and a municipal fleet manager at the same time. Each buyer type has a different application, a different purchasing process, and different information needs before they will make contact. Dealers who build landing pages or campaign content around specific vocational applications — construction, utility, municipal — give each buyer type a path that feels relevant to their situation rather than a generic commercial truck pitch.
The Replacement Cycle Pressure That Is Not Going Away
The 12.8-year average fleet age that S&P Global and NTEA are reporting is not a single-year anomaly. It reflects five years of compressed new vehicle supply, extended replacement cycles, and deferred purchases that built up during 2020 through 2024. That deferred demand does not evaporate — it converts into buying activity as maintenance costs reach the point where replacement is cheaper than continuing to operate aging equipment. Fleet Rabbit’s maintenance cost analysis puts the crossover point at roughly the 10-year mark for most commercial applications, where annual maintenance costs begin to exceed the cost of financing a replacement unit.
For dealers, this means the vocational replacement cycle pressure that is driving Q4 2026 buying is not a one-quarter event. Construction companies, utility operators, and government fleets that are replacing units in Q4 2026 are the front edge of a multi-year replacement wave. Dealers who build relationships with these buyer segments now — and who demonstrate that they understand vocational applications, not just retail transactions — are positioning themselves for recurring business rather than a single sale.
The 12.8-year average fleet age is the front edge of a multi-year replacement wave, not a one-quarter event. Dealers who build vocational buyer relationships in Q4 2026 are positioning for recurring business.
Is Your Marketing Reaching the Buyers Who Are Actually Active?
If your current marketing is aimed at the broad commercial truck market without segment-specific messaging, you may be generating awareness with buyers who are not purchasing right now while the active vocational, construction, and government segments are not seeing anything relevant from your dealership.
Book a 15-Minute Call with our team. We will look at how your current inventory and marketing is positioned relative to the segments that are actively buying in Q4 and show you what segment-specific adjustments typically do to inquiry volume. No pitch, no obligation.
Email us directly: info@buzznerd.com
Sources
Trucks, Parts, Service — 2026 Commercial Vehicle Market Outlook: NTEA & S&P Analysis
MonitorDaily — Market Outlook 2026: Trucks and Trailers
Hackney — Navigating the 2026 Commercial Truck Dealer Market
Work Truck Online — Q2 2026 Commercial Vehicle Data Report
Fleet Rabbit — Aging Fleet Vehicles 2026: True Cost Maintenance Data
ACT Research — 2026 Trucking Industry Forecast and Market Outlook
FAQ
Question: Which commercial truck segments are growing in Q4 2026?
Answer: Vocational segments including construction, utility, energy, and government fleets are the most active buyers in Q4 2026. Long-haul and over-the-road carrier demand remains soft due to subdued freight rates. The two-speed market means dealers who adjust their marketing toward vocational applications are targeting the active half of the buyer pool.
Question: Why are government and municipal fleets buying commercial trucks in Q4 2026?
Answer: Government registrations were the only vocational category to show year-over-year growth in 2025, a trend continuing into 2026. Municipal fleet managers with fiscal year budgets that expire December 31 create concentrated Q4 buying urgency. Dealers visible to government procurement before Q4 begins are more likely to be in consideration during the buying window.
Question: What is driving construction and infrastructure fleet demand in 2026?
Answer: Federal Infrastructure Investment and Jobs Act spending continues to generate equipment demand from contractors executing multi-year projects. Construction buyers arrive with defined specs — body type, payload, axle configuration — and are purchasing against project requirements rather than browsing. Dealers who present vocational inventory with complete spec detail are better positioned to convert these inquiries.
Question: What does the 12.8-year average fleet age mean for commercial truck dealers?
Answer: The average US commercial truck fleet age of 12.8 years, the highest since the Great Recession, reflects deferred replacement cycles from 2020 through 2024. It represents accumulated buying pressure that converts into purchasing activity as maintenance costs exceed the cost of replacement. For dealers, it signals a multi-year replacement wave in vocational segments rather than a single-quarter buying event.
Question: How should commercial dealers adjust their marketing for Q4 2026 segment conditions?
Answer: Dealers should build segment-specific messaging for construction, utility, and government buyers rather than relying on broad commercial truck marketing. This means leading with application and spec detail in listings, acknowledging fiscal year budget urgency in Q4 communications, and positioning service capability as part of the value for multi-unit vocational buyers.